ServicesInvestment Management
Investment Management in Holmdel, NJ
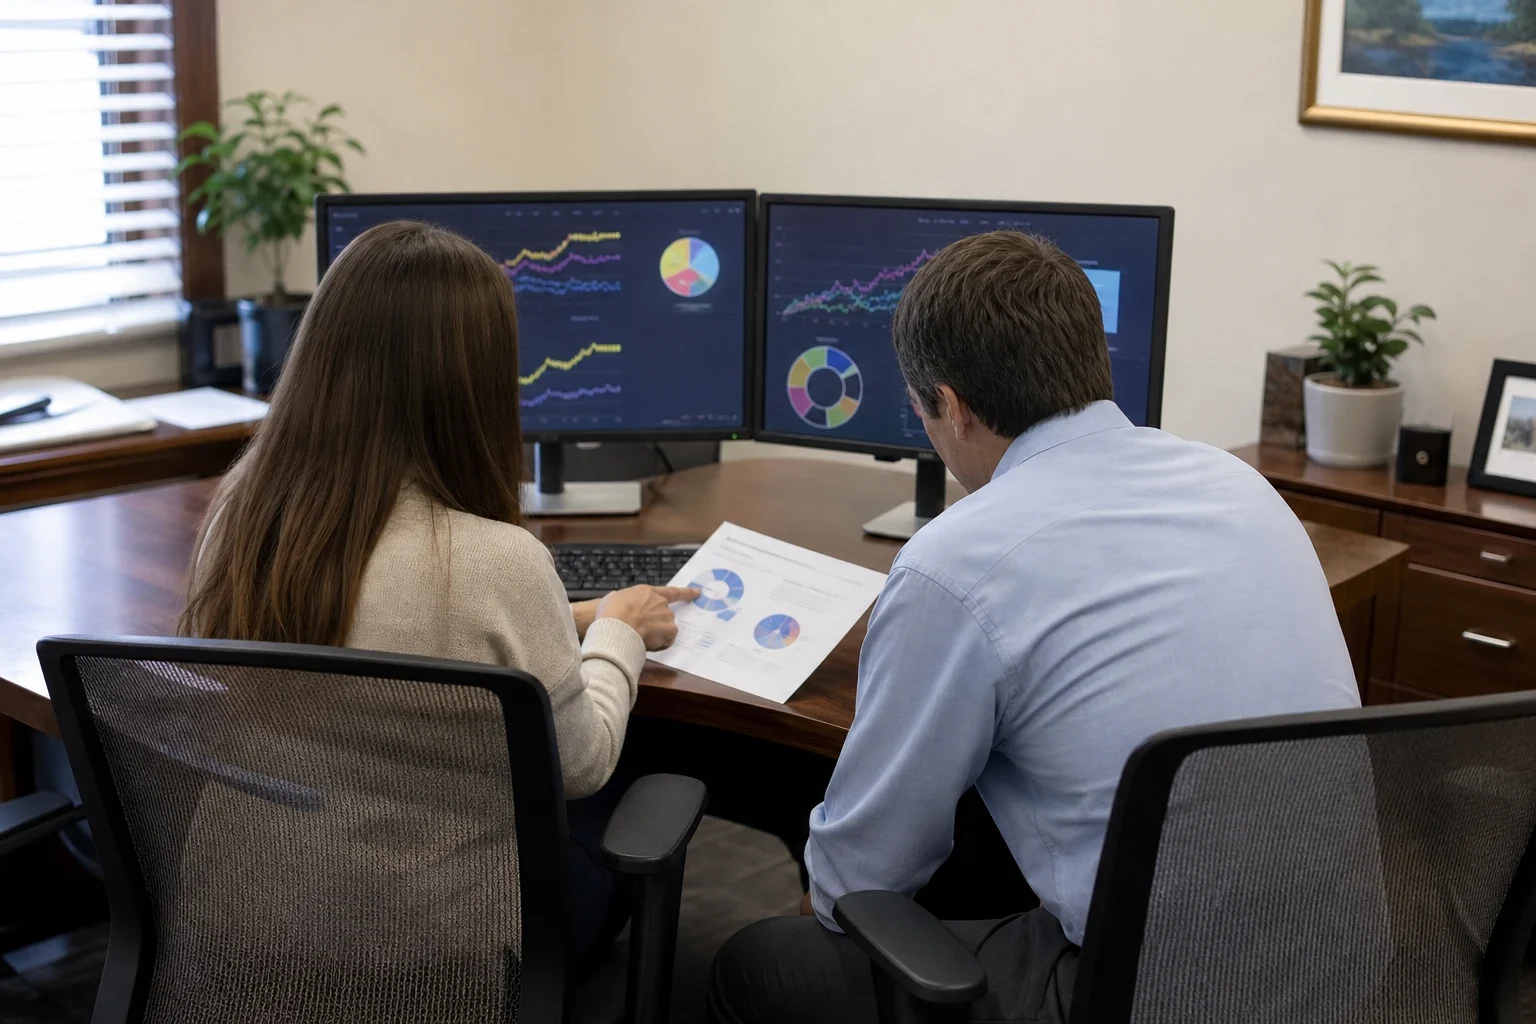
We manage your portfolio against a written target allocation, watch for drift, costs and tax drag, and keep a dated record of each review. You see what we found in your accounts, what we changed and why, before and after every adjustment.
What investment management covers
Investment management is the ongoing work of running your accounts: choosing the mix of stocks, bonds and cash, picking the funds that hold it, rebalancing when markets push the mix off target, and placing each holding in the account type where it is taxed least. It is narrower than wealth management, which adds estate, insurance and cash-flow questions on top.
Most portfolios we review were never designed as one whole. A 401(k) from an old employer, an IRA opened years ago and a taxable brokerage account often hold overlapping funds with different expense ratios, so the real allocation is not what anyone intended. Our first job is to show you that picture plainly.
Every review is documented. We capture account snapshots before a change, note the reason for each trade, and capture them again after, so you can follow the work without taking our word for it.
What the work includes
Consolidated holdings review
We pull statements from every account and map them into one view. That exposes fund overlap, hidden concentration in a single sector or company, and cash sitting idle.
Written target allocation
Your stock, bond and cash targets are set from your goals, time horizon and how much decline you can sit through. We write the targets down with a tolerance band for each, so rebalancing follows a rule instead of a mood.
Rebalancing and drift monitoring
When an asset class moves outside its band, we trade it back. Where possible we use new contributions or dividends first, which limits selling and the capital gains it can trigger.
Asset location
Bond funds and other income-heavy holdings generally belong in tax-deferred accounts, while broad stock index funds tend to be more efficient in taxable ones. We place holdings deliberately and coordinate with our tax management work.
Cost and fund review
We list the expense ratio of every fund you own and flag share classes that cost more than an equivalent version. Small differences compound over decades.
Documented change log
Each adjustment is recorded with before and after snapshots and a short note on the reason. You keep the record.
Signs your portfolio needs attention
You can't name your allocation
If you do not know your current split between stocks and bonds across all accounts, it has probably drifted. A long run in stocks can quietly leave a portfolio far more aggressive than planned.
Old accounts scattered around
Retirement plans left at former employers often sit in default funds nobody revisited. They also make the full picture hard to see.
One stock dominates
Company shares from equity compensation or an inherited position with a low cost basis can grow into an outsized risk. Unwinding it takes planning around taxes.
Large cash balances
Cash held for years while waiting for a better entry point loses ground to inflation.
Retirement is getting close
The years just before and after retirement are when a sharp decline does the most damage, because withdrawals can lock in losses. Your mix and withdrawal order deserve a fresh look, often alongside retirement planning.
How we work, step by step
- 1
Introductory meeting
We talk at our office, by phone or by video about your goals and what you hold. You bring recent statements, and we explain how we would approach your accounts.
- 2
Documented findings
We map every holding and capture snapshots of where things stand. You get a written summary of what we found: allocation, overlap, costs, concentration and tax exposure.
- 3
Proposed changes, explained
We lay out each recommended trade, the reason for it and any tax it may create. Nothing moves until you agree.
- 4
Implementation and record
Approved trades are placed, then we capture the accounts again so you can compare before and after. Ongoing reviews follow the same pattern, each one added to your record.
What affects the cost
There is no single price for investment management, because the work varies a great deal from one client to the next. We explain how our pricing is set during the introductory meeting, in writing, before you commit to anything. These are the main things that move it.
- Number and type of accounts
- One IRA is simpler than a mix of 401(k), Roth, taxable, trust and custodial accounts that must be managed as one portfolio.
- Complexity of holdings
- Concentrated stock, restricted shares, many small tax lots or older positions with low cost basis take more analysis to unwind carefully.
- Tax coordination
- Tax-loss harvesting, watching wash-sale rules and managing gains across accounts add work, and value, for taxable portfolios.
- Reporting and review frequency
- How often you want formal reviews and documented updates affects the time involved.
Investment management questions
Something not covered here? (732) 719-2097
Do I have to move all my accounts to work with you?
Not necessarily. Some accounts, such as a current employer's 401(k), may stay where they are, and we can still factor them into your allocation. We will explain which accounts make sense to consolidate and why.
Will selling my current funds create a tax bill?
It can in taxable accounts, which is why we look at cost basis before recommending any sale. Trades inside IRAs and 401(k)s do not create current tax. Sometimes the right move is a gradual transition rather than selling everything at once.
How often do you rebalance?
We monitor drift continuously against the tolerance bands in your written targets and rebalance when a band is crossed, not on a fixed calendar. That avoids unnecessary trading in quiet markets and acts promptly after big moves.
Can you promise a certain return?
No honest advisor can. Markets go down as well as up. What we control is your allocation, your costs, tax efficiency and discipline during declines, and we document each of those so you can judge the work.
What do the records you keep actually look like?
For each review you get account snapshots from before and after any change, a list of the trades placed and a plain note explaining why. Over time this becomes a running history of your portfolio and the decisions behind it.
See what's really in your portfolio
Bring your latest statements to an introductory meeting at our office, or join by phone or video from Middletown, Marlboro or nearby. We will walk through what we would look at first.